
Home › Coverages 12 Coverages Explained › Business Owner's Policy for Plumbers
A business owner's policy for plumbing shops
A business owner's policy for plumbers bundles general liability, commercial property for your shop and parts stock, and business income into one package, and it often costs less than buying those pieces separately. Not every plumbing business qualifies, and a BOP doesn't include workers' comp, commercial auto or professional liability.
- Since 2003
- 12+ A-rated carriers
- 28 states
- Independent agents
Start your plumber insurance quote
Takes about a minute. A licensed agent follows up.
Licensed in 28 states · NPN 7642818 · Since 2003
What a business owner's policy covers for a plumbing shop
A business owner's policy, or BOP, is a package built for smaller businesses. For a plumbing shop, it bundles three coverages that would otherwise be separate policies, and that bundle often costs less than buying them one by one.
General liability
The liability side pays for injuries to other people and damage to their property that your work causes, plus your legal defense. It carries the same kinds of exclusions a standalone general liability policy does, so read our general liability page for how faulty work and resulting damage are treated.
Commercial property
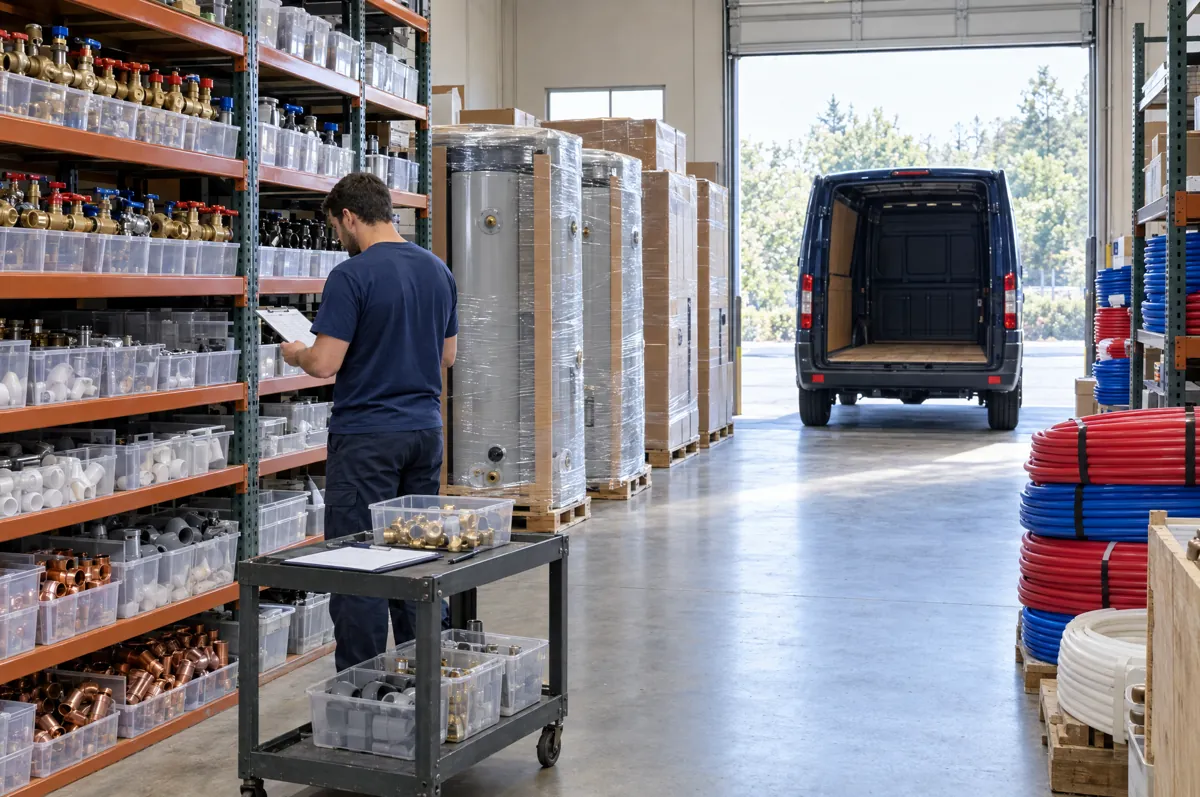
The property side covers your shop, warehouse and the stock inside them: fittings, valves, water heaters waiting to go out, and the shelving and office equipment that run the business. If you rent your space, it covers what you own inside it. If you own the building, it can cover the building too.
Business income
If a covered loss shuts your shop down, business income coverage pays the income you lose while the damage is repaired. That's the coverage that keeps payroll and rent moving while the parts room is rebuilt.
Equipment breakdown
Equipment breakdown coverage can often be added to a BOP. It's built for the sudden mechanical or electrical failure of equipment like the air compressor in your shop or the boiler that heats your building. Many BOPs don't include it automatically, so ask.
| What it covers | What it usually doesn't |
|---|---|
| Injuries and property damage your work causes to others | Injuries to your own employees (that's workers' comp) |
| Your shop, warehouse and the parts stock inside | Your vans and trucks (that's commercial auto) |
| Shelving, office equipment and furniture | Design and advice mistakes (that's professional liability) |
| Income you lose while covered damage is repaired | Data breaches and cyber attacks (that's cyber coverage) |
| A failed shop boiler or compressor, if you add equipment breakdown | Equipment breakdown, unless you add it |
| Your building, if you own it and list it | Tools and machines that travel to jobs, on many policies |
How a BOP claim works for a plumbing shop
These are made-up examples. A real claim depends on your policy's terms, exclusions and limits.
The parts room fire
Example scenario: A battery charger shorts out overnight in a shop's parts room. The fire ruins the shelving and most of the fittings and valve stock, and smoke damage closes the shop for three weeks. The property side of a BOP may pay to replace the stock and shelving, and business income coverage may pay the income the shop loses while repairs are made.
The shop boiler in January
Example scenario: The gas boiler that heats a plumbing shop's warehouse cracks a heat exchanger during a cold snap. If the owner added equipment breakdown coverage, it may pay to repair or replace the boiler. Without that add-on, many property policies won't respond to a mechanical failure on its own.
Limits and what drives the price of a BOP
A BOP has two kinds of limits. The liability side has per-occurrence and aggregate limits like a standalone GL policy. The property side has a limit for your building, if you own it, and one for your business property and stock.
Set the property limit at what it would cost to replace everything in the shop today, not what you paid for it years ago. Count the parts room, shelving, office gear and anything waiting to go out on jobs.
What moves the price:
- The value of your building and contents
- Your revenue and the kind of plumbing work you do
- Your claims history and the liability limits you choose
- Optional add-ons like equipment breakdown
| Coverage | What drives the price | Typical range |
|---|---|---|
| Business owner's policy, plumbing contractors | Property value, revenue, work mix, limits | Median $213 a month, about $2,559 a year (published plumber median) |
Your price depends on payroll, revenue, claims history, the work you do and the limits you choose. Get a quote for your plumbing business →
Which plumbing businesses fit a BOP best
A BOP fits best when you have a physical shop or warehouse and the work is on the lower-hazard side.
- Residential service and repair shops are the classic fit: a shop, a parts room, a few vans and work that stays inside homes. See residential plumber insurance.
- Commercial contractors often start on a BOP and outgrow it as revenue, headcount and contract demands climb. See commercial plumbing contractor insurance.
- Drain and sewer shops that dig may not qualify, and may need separate policies built for excavation work.
A BOP still leaves your vans, tools and crew to other policies. Most shops pair it with commercial auto, a tools and equipment floater and workers' comp.
Cyber: the coverage a BOP leaves out
If you take card payments in the field or keep customer addresses and gate codes in dispatch software, you hold data worth stealing. Cyber coverage often isn't part of a BOP. The Hartford, for one, lists it among the coverages its BOP doesn't include. Ask us whether a separate cyber policy makes sense for the way your shop handles payments and records.
BOP requirements by state
We haven't found a state that requires a BOP. The push usually comes from your landlord or lender instead. Your shop lease may ask for proof of liability and property coverage, and a bank financing your building may want to be listed on the property side. Read the lease before you set limits.
Your state matters most for the property side, because weather drives so many shop losses. Two examples from our state research:
- Alabama. The April 27, 2011 outbreak produced 62 confirmed tornadoes across the state, including an EF4 that tracked more than 80 miles from Tuscaloosa toward Birmingham. See Alabama plumber insurance.
- Kentucky. The July 2022 flash flood in Eastern Kentucky dropped 14 to 16 inches of rain. See Kentucky plumber insurance.
Ask how your property coverage treats flood and wind before storm season. Find your own state's rules on our state pages. Get a quote for your plumbing business →
Coverage that pairs with a BOP
BOP questions from plumbers
Is a business owner's policy the same as general liability?
Can a plumbing contractor get a BOP?
Does a BOP cover my work van?
Does a BOP include workers' comp?
How much does a BOP cost for a plumbing business?
Does a BOP cover a cyber attack?
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.