
Home › Coverages 12 Coverages Explained › Tools & Equipment Insurance for Plumbers
Tools and equipment insurance for plumbers
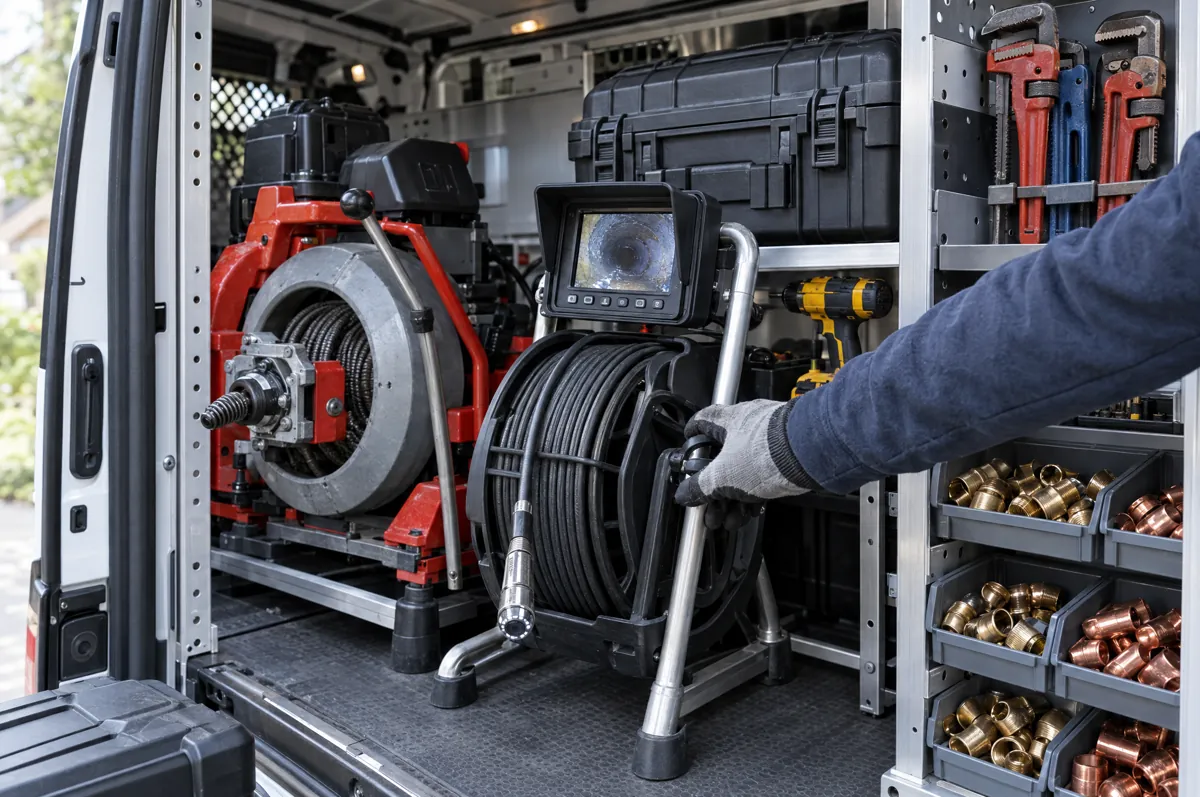
Tools and equipment insurance for plumbers, often sold as contractors equipment or inland marine coverage, pays to repair or replace gear that's stolen or damaged on the truck, at the job or in storage. Your auto policy usually covers the van, not the jetter, camera or press tools riding in it.
- Since 2003
- 12+ A-rated carriers
- 28 states
- Independent agents
Start your plumber insurance quote
Takes about a minute. A licensed agent follows up.
Licensed in 28 states · NPN 7642818 · Since 2003
How contractors equipment insurance works for plumbers
Contractors equipment insurance is a type of inland marine coverage, and a "floater" in insurance terms means it follows your property wherever it goes. Your drain machine is covered on the truck, at the customer's house, and on the shelf back at the shop. If it's stolen or damaged by a covered cause, the policy pays to repair or replace it, minus your deductible.
Most policies split your gear into two groups:
- Scheduled equipment. Bigger-ticket items listed by name, often with a serial number and a set value. Think hydro-jetters, sewer camera systems, pipe locators and threading machines.
- Unscheduled small tools. Hand and power tools covered as a group, usually with a cap on any single item.
Industry guidance notes that items worth more than $2,500 may need to be scheduled on their own. If your press tool kit is worth more than the per-item cap, list it.
Why a separate policy at all? Commercial auto covers the van and gear bolted to it. The loose tools, press kits, camera rigs and parts riding inside usually aren't covered by the auto policy.
Questions to settle before you buy
Floaters aren't standardized the way a general liability form is, so two quotes with the same limit can behave very differently at claim time. Ask each carrier the same questions:
- Are tools your techs own covered while they're working for you?
- Is rented or borrowed equipment covered, such as a rented mini-excavator or a borrowed jetter?
- What's the per-item cap on unscheduled tools, and is it high enough for your newest press kit?
- Does the deductible apply per item or per loss?
Lay the answers side by side. A quote that costs less up front often has tighter conditions.
| What it covers | What it usually doesn't |
|---|---|
| Jetters, sewer cameras and locators listed on the schedule | The van itself and racks bolted to it (that's commercial auto) |
| Hand and power tools as a group, up to the per-item cap | Water heaters, fixtures and pipe you're installing (that's an installation floater) |
| Theft from a job site, depending on the policy's terms | Your shop building (that's property or a BOP) |
| Gear damaged in transit between jobs | Injuries or damage your tools cause to others (that's general liability) |
| Equipment in storage at your shop or yard | Items worth more than the per-item cap that you never scheduled |
| Press tool kits and expansion tools | Theft from a vehicle that doesn't meet the policy's conditions |
What a tools claim looks like
These are made-up examples. How a real claim is handled depends on your policy's wording and conditions.
The apartment parking lot
Example scenario: A tech parks his van overnight in an apartment lot after a late emergency call. By morning, the side door has been pried and the press tool kit and a pipe locator are gone. A floater with both items covered would typically pay to replace them, minus the deductible, as long as the theft meets the policy's conditions for vehicles.
The rotted porch step
Example scenario: A sectional drain machine goes through a rotted back-porch step while two techs are carrying it to a basement cleanout. The frame cracks and the motor mount bends. Accidental damage like this is often covered by a contractors equipment policy, depending on the form.
Limits, deductibles and what drives the price
Your limit is the total value of the gear you insure: the scheduled items plus a blanket amount for small tools. Build the list from your real inventory. Walk each van with your techs, photograph the gear, and record serial numbers and what it would cost to replace.
Keep the schedule current
The schedule only works if it matches what's actually in your vans. Keep one list for the whole shop:
- Walk every van and the shop shelves once a quarter.
- Add every machine the week you buy it, with the serial number, photo and receipt.
- Remove gear you've sold or scrapped, so you're not paying to insure it.
- Store the list somewhere other than the van, so a theft doesn't take the records too.
Ask how the policy values a loss. Some pay the cost to replace with new gear, and others subtract for age and wear. That choice can make a big difference on a five-year-old sewer camera.
| Coverage | What drives the price | Typical range |
|---|---|---|
| Tools and equipment, construction contractors including plumbers | Value of your gear, deductible, where it's kept | Median $42 a month (published industry data) |
Your price depends on payroll, revenue, claims history, the work you do and the limits you choose. Update the schedule every time you buy a machine, not at renewal. Get a quote for your plumbing business →
Which plumbers need tools coverage most
Any shop whose gear would be hard to replace out of pocket should look at it. Three kinds of plumbing work lean on it hardest:
- Drain and sewer shops carry the most expensive equipment per van: hydro-jetters, camera systems and locators that can cost more than the truck. See drain and sewer contractor insurance.
- Residential service shops spread press tools, drain machines and van stock across several vehicles that park at techs' homes overnight. See residential plumber insurance.
- Commercial contractors keep threading machines and job-site gang boxes on site for weeks at a time.
The growth angle is simple. Every new van adds another few thousand dollars of gear to the schedule, and a single stolen jetter can sideline a crew for a week while you shop for a replacement.
Tools coverage by state
No state license rule we've found requires tools coverage. If you finance or lease a big machine, ask whether the lender requires it.
Where your state matters is weather. Storms and floods damage vans, yards and the gear inside them, so ask how your policy treats flood before the season starts. Two examples:
- Florida. Hurricane Ian pushed 10 to 15 feet of storm surge above ground level into Fort Myers Beach in 2022. See Florida plumber insurance.
- Iowa. The August 2020 derecho brought damage consistent with 130 to 140 mph winds in Cedar Rapids, and many places saw damaging wind for 30 to 60 minutes. See Iowa plumber insurance.
For the rules where you work, see our state pages. Get a quote for your plumbing business →
Coverage that pairs with tools and equipment
Tools insurance questions from plumbers
Are my tools covered if they're stolen from my van?
Is inland marine the same as tools insurance?
Do I have to list every tool on the policy?
How much does tool insurance cost for a plumber?
Does tools insurance cover materials I'm installing?
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.